What the proposed new ‘RRSP for life’ would mean for Canadians and their taxes - Toronto Star
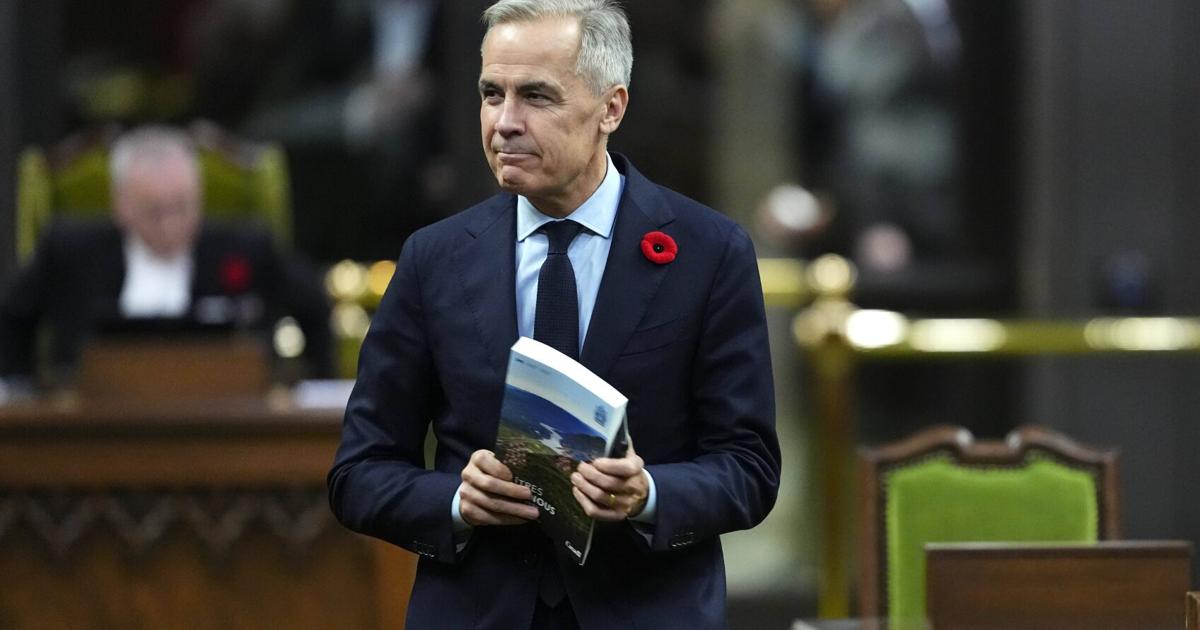
If passed into law, the new rules would mean Canadians would no longer have to convert RRSPs to RRIFs by age 71.
Prime Minister Mark Carney arrives in the House of Commons on Parliament Hill before the tabling of the federal budget in Ottawa on Thurs., Nov. 5.
As part of Thursday’s federal budget announcement, the Carney government announced plans to merge tax rules for registered retirement savings plans (RRSPs) and registered retirement income funds (RRIFs) into a single “RRSP for life.”
The proposal is part of the government’s larger effort to simplify taxes for Canadians.
If passed into law, the new rules would mean Canadians would no longer have to convert RRSPs to RRIFs by age 71 — significantly reducing paperwork without changing how the accounts fundamentally work.
There are no new tax implications for the RRSP for life. Canadians older than 71 would still be required to make minimum annual withdrawals from their RRSPs, and those withdrawals would still be taxed as income.
Under the proposed rules, when an RRSP holder dies, a surviving spouse or common-law partner named as a “successor holder” would take ownership of the account tax-free.
Under the current system, Canadians can name a beneficiary for an RRSP. When they die, the RRSP is collapsed and the balance is treated as income on their final tax return, which can trigger a significant tax bill. If the beneficiary is a surviving spouse or common-law partner, the money from the RRSP can be transferred to their own RRSP or RRIF (or an eligible annuity) on a tax-deferred basis, which avoids an immediate tax hit. If the surviving spouse chooses instead to put the money into a chequing or savings account, they could face a big tax hit because it’s treated as income.
Under the new proposal, the RRSP for life will continue if a spouse or common-law partner is named as a successor and the transfer will happen automatically. The surviving spouse could keep the money in the account tax-deferred, or take the money out and pay income tax. “It basically allows a much easier transition after the death of a spouse,” said Jamie Golombek, managing director of tax and estate planning at CIBC.
In an email to the Star, an official with the Department of Finance said a successor wouldn’t be obligated to maintain the RRSP. “They would have the option to transfer the plan property to another RRSP under which they are the holder or to purchase a lifetime annuity as a final plan settlement.”
Experts agree these changes are tax neutral and ultimately aim to simplify the administrative process.
Jennifer Robson, a political management professor at Carleton University in Ottawa, doesn’t believe the new RRSP rules will be life-changing for people’s retirement plans, but said it will simplify some of the decision-making. “A simplified tax system is easier for people to use and abide by, and easier and lower cost for governments to administer,” Robson said.
Chartered professional accountant Stefanie Ricchio noted some details remain unresolved until consultations end. “There could be some issues that arise from a tax perspective,” Ricchio said. For example, RRIF withdrawals are currently eligible for the pension income credit and pension income splitting with a spouse, but RRSP withdrawals are not.
Golombek called the proposed changes “a great idea in terms of administrative simplicity,” adding Canadians likely won’t see the RRSP for life come into play any time soon. “I think this is a couple of years away at least.”
The government’s RRSP for life proposal is in consultation until Jan. 8, 2027. Canadians can share their views with the Department of Finance Canada at RRSP-consultation-REER@fin.gc.ca.
Lora Grady is a personal finance reporter for the Star. Reach her via email at lgrady@thestar.ca.